Category: For Buyers

  • Buy Before You Sell: How to Make Your Next Offer Strong as Rates Climb

    Buy Before You Sell: How to Make Your Next Offer Strong as Rates Climb

    The short version: mortgage rates are moving higher, and for homeowners who want to buy their next home before selling the one they’re in, planning matters more than ever.

    Mortgage rates posted their largest weekly increase in four years last week, according to Freddie Mac’s Primary Mortgage Market Survey (PMMS), as reported by The Wall Street Journal on October 1, 2026. The Journal described the bond-market selloff as “dealing blow after blow to a limping housing market.”

    Line chart of the weekly average 30-year fixed mortgage rate from October 2025 to October 2026, falling to a low of 5.98% in February 2026 and rising to 7.28% on October 1, 2026, up 0.25 points in one week.

    Source: Freddie Mac Primary Mortgage Market Survey (PMMS), as reported by The Wall Street Journal, October 1, 2026. Data reflects historical national averages for informational and educational purposes only. This information does not constitute a credit quote, a commitment to lend, or an offer of specific credit terms. Actual interest rates, APRs, and loan programs vary widely based on individual credit history, debt-to-income ratios, down payments, and market conditions. The author is a licensed real estate professional, not a mortgage lender. Please consult a licensed mortgage loan originator for personalized financing options and current rate qualifications.

    For many homeowners in Fairfield County, the rate is only part of the question. The bigger one is timing: how do you buy your next home before you sell the one you’re in?

    Why Buying First Matters in Our Local Market

    In a market where the right homes still draw strong buyer interest, an offer that depends on selling another house first is most likely the weakest one on the table. Sellers want certainty. A buyer who can close without a home-sale contingency has a real advantage, especially on the homes everyone wants.

    Buying first also means one move instead of two, no temporary rental, and time to settle into the new house before listing the old one. The tradeoff is that, for a period of time, you may be responsible for two homes. With rates moving higher, that piece deserves a careful look before you write an offer.

    That’s why this conversation starts with financing. Below, guest author Francine Silberman of William Raveis Mortgage shares how she plans it out.

    Infographic: Buying First means one move instead of two, no temporary rental, and time to settle in before listing the old home. The tradeoff: for a period of time you may be responsible for two homes, with mortgage, taxes, insurance and maintenance on both. With rates moving higher, this deserves a careful look before you write an offer.

    Guest Author: Francine Silberman, William Raveis Mortgage

    My personal mission is to educate buyers and sellers so they can successfully navigate today’s challenging real estate market. Comprehensive, upfront planning is key to a smooth and positive experience.

    One of the most frequent questions I address is how a seller can strategically purchase a new home before selling their existing one. The exact plan always requires a case-by-case analysis, but there are baseline factors I evaluate with every client, whether or not they’re using traditional mortgage financing.

    An Initial Assessment of Assets and Funds

    1. Do you have sufficient, documentable liquid funds? This includes your down payment, closing costs, property taxes and first-year insurance premium.
    2. Are funds available for the buyer agent commission? If you’re responsible for paying it before your current home sells, it needs to be part of the plan.
    3. Can you document post-closing reserves? Most lenders require a cushion to protect against unexpected costs from life events.

    If Your Equity Is Tied Up in Your Current Home

    If most of your equity is in your current home, or you’d rather not liquidate investments, I shift to a solution-oriented look at alternative funding options:

    • Home equity line of credit (HELOC): Is there a viable existing HELOC that could serve as a bridge?
    • Gifted funds: Can a family member provide a formal gift or a structured loan?
    • Retirement plan loans: Does your qualified 401(k) plan offer a loan feature?
    • Asset-backed lending: Can you secure a loan against your investment portfolio?
    • Dual financing: Can you qualify for a first mortgage and a new HELOC on the home you’re buying at the same time?
    • The Raveis Purchase Program: Would William Raveis’ own program make sense to unlock your equity and release you from your current home obligations?

    A Review of Income and Expenses

    Often, the right plan combines several of these options. To get there, I review your current income sources to confirm you can comfortably carry both your existing financial commitments and the expected monthly costs of the new home.

    Contemplating a buy then sell strategy requires precision. Scheduling time with me to evaluate the options that best suit your circumstances is time well spent, and the key to making your next offer strong and highly competitive.

    — Francine Silberman, William Raveis Mortgage


    Where the Sale Side Comes In

    Financing is one half of the plan. The other half is the sale of your current home, and the two need to be timed together. That’s where my role as your real estate agent comes in:

    • Pricing and preparation before you buy. Knowing what your current home is likely to sell for, and what it needs before it goes on the market, gives you and your lender real numbers to plan with.
    • Timing the listing. If you buy this fall, we’ll plan the right launch window for your current home so it goes to market fully prepared and priced to perform.
    • Negotiating terms that buy you time. A longer closing or a rent-back on either side can take pressure off the in-between period.
    • Keeping everyone in sync. Your lender, your attorney and both transactions stay on the same timeline, so nothing slips.
    Real estate agent meeting with homeowners outside their Fairfield County, Connecticut home to plan a buy-before-you-sell move
    Two transactions, one coordinated plan.

    Buy Before You Sell: Quick Answers

    Can I buy a new home before selling my current one?

    Yes. Many Fairfield County homeowners do. Depending on your situation, the plan may draw on liquid funds, an existing or new HELOC, asset-backed lending, a 401(k) loan, gifted funds, dual financing or the Raveis Purchase Program. The right mix comes from a case-by-case review of your assets, equity, income and expenses with a mortgage professional.

    Why is an offer without a home-sale contingency stronger?

    Sellers want certainty. An offer that depends on selling another house first is often the weakest one on the table, while a buyer who can close without that contingency has a real advantage, especially in competitive towns like Darien, New Canaan and Rowayton.

    When should I list my current home if I buy first?

    If you buy in the fall, it often makes sense to prepare your current home over the winter and launch in the spring market. A longer closing or a rent-back on either side can also take pressure off the in-between period.

    Start With Two Conversations

    If you’re thinking about buying before you sell, the best first step is a short conversation with each of us: one about your financing options, and one about your home, your timing and the market. Together, we’ll help you build a plan that makes your next offer strong, even as rates move.

    All financing options are subject to credit approval and program guidelines. Please consult a licensed mortgage loan originator about your specific situation.
  • More Than Opening Doors: What Your Buyer’s Agent Really Does Before You Make an Offer in Darien

    More Than Opening Doors: What Your Buyer’s Agent Really Does Before You Make an Offer in Darien

    Most people think a buyer’s agent unlocks doors, books showings and sends over the paperwork. That’s the part you see. It’s also the smallest part of the job.

    The real work happens behind the scenes, in town files, inspection reports and fine print. It all has to come together in a matter of days, and when something gets missed, the stakes are high:

    • The deal falls apart late in the process, after you’ve paid for inspections and legal fees and lost weeks you didn’t have.
    • Your reputation takes a hit. In close-knit communities like ours, word travels. A buyer who backs out late can have a harder time being seen as a strong, reliable buyer the next time around.
    • You get locked into a bad deal. If your deadlines pass before the problems surface, you can end up committed to a price, terms or repairs that no longer make sense.

    My role is to keep all of those moving parts organized and on schedule, and to make sure the right professionals are looking at the right things at the right time.

    Septic system inspection during a buyer’s due diligence
    Touring is the part you see. The real work happens behind the scenes.

    What You See vs. What’s Happening Behind the Scenes

    What you seeWhat I’m coordinating
    A beautiful finished basementPulling the permit history so your attorney and inspector can confirm it was approved and closed out
    A big backyard, perfect for a poolGathering zoning and wetlands information so you can confirm your plans with the town early
    A charming 1950s colonialMaking sure the right inspections are scheduled, like oil tank, septic and radon
    A home steps from the waterFlagging the flood zone and connecting you with insurance agents for quotes
    A signed seller’s disclosureWalking through it with you and noting questions for your inspector and attorney
    “Offer accepted!”Keeping your inspectors, attorney, lender and insurer on the same timeline

    1. Town Records, Reviewed Before You Fall in Love

    Every town keeps a record of what’s been approved and what hasn’t. An open permit can delay a closing, and a zoning limit can affect future plans like an addition or a pool.

    Before we write an offer, we gather the key public records together, including building permits, zoning information, wetlands and coastal considerations, and the property card, and anything that needs a closer look gets flagged. From there, your attorney reviews the legal details, and the town’s building and zoning offices can confirm specifics. That way, the questions get raised before you’re emotionally and financially invested, not after.

    Reviewing house plans and permit drawings
    Permits, zoning and plans, reviewed before you fall in love.

    2. Septic or Sewer: The Right Questions, Asked Early

    Many Darien and New Canaan homes are on private septic rather than town sewer, and that can affect your inspection, your future costs and even plans to add bedrooms.

    My role: requesting the available septic records and making sure a qualified septic inspector is on the schedule during your inspection period. For homes on sewer, your attorney gets a heads-up to confirm there are no outstanding assessments.

    3. The Full Picture on a Coastal Home

    In Darien, Rowayton and Norwalk, the flood zone can change the math on a house.

    My role: finding the FEMA flood designation, requesting an elevation certificate if one exists, and connecting you with insurance professionals, so you have real quotes while there’s still time to negotiate.

    Darien waterfront on Long Island Sound
    Near the water? The flood zone can change the math on a house.

    4. An Inspection Plan, Coordinated From Day One

    A general inspection is only the starting point. Depending on the home, your inspectors may recommend radon, well water, an oil tank sweep, or chimney, roof, pool and wood-destroying insect inspections. That can mean several specialists, each with their own schedule, all reporting back before your deadline.

    My role: helping you decide which inspections to consider, introducing you to qualified professionals, and keeping every appointment on the calendar.

    5. The Seller’s Disclosure, Read Together

    Connecticut sellers must provide a Residential Property Condition Report. What a seller says about water, the roof’s age or past repairs is often the best clue about where to look.

    My role: going through it with you line by line and noting anything worth a closer look, so your inspector knows where to focus and your attorney can follow up on anything that needs it.

    6. Your Pit Crew, Working in Sync

    In Connecticut, real estate attorneys handle the contract and closing, while your lender, inspectors and insurance agent each have their own piece of the puzzle.

    My role: working alongside your attorney and the rest of your team so information flows quickly and deadlines don’t slip. You’re always free to choose your own professionals. If you’d like recommendations, you’ll get names of people my clients have had great experiences with in Darien, New Canaan and Rowayton.

    7. What We Learn, Turned Into a Stronger Position

    Once the reports come in, the real decisions begin: what may be a dealbreaker, what may be worth negotiating, and what’s just an old house being an old house.

    My role: helping you sort through it all and, working with your attorney, pursuing options like a repair credit, a price adjustment or better terms.

    Your Due Diligence Checklist, and How I Help

    • ✔ Building permits and zoning: records gathered, questions flagged for your attorney
    • ✔ Sewer or septic: records requested, inspection scheduled
    • ✔ Flood zone and insurance: designation checked, quotes coordinated
    • ✔ Radon, well, oil tank and specialty inspections: scheduled and coordinated
    • ✔ Seller’s Property Condition Report: reviewed together
    • ✔ Attorney, lender, inspector and insurance agent: connected and in sync from day one

    Together, we’ll find the home you love, and I’ll help you make an educated, smart and strategic purchase.

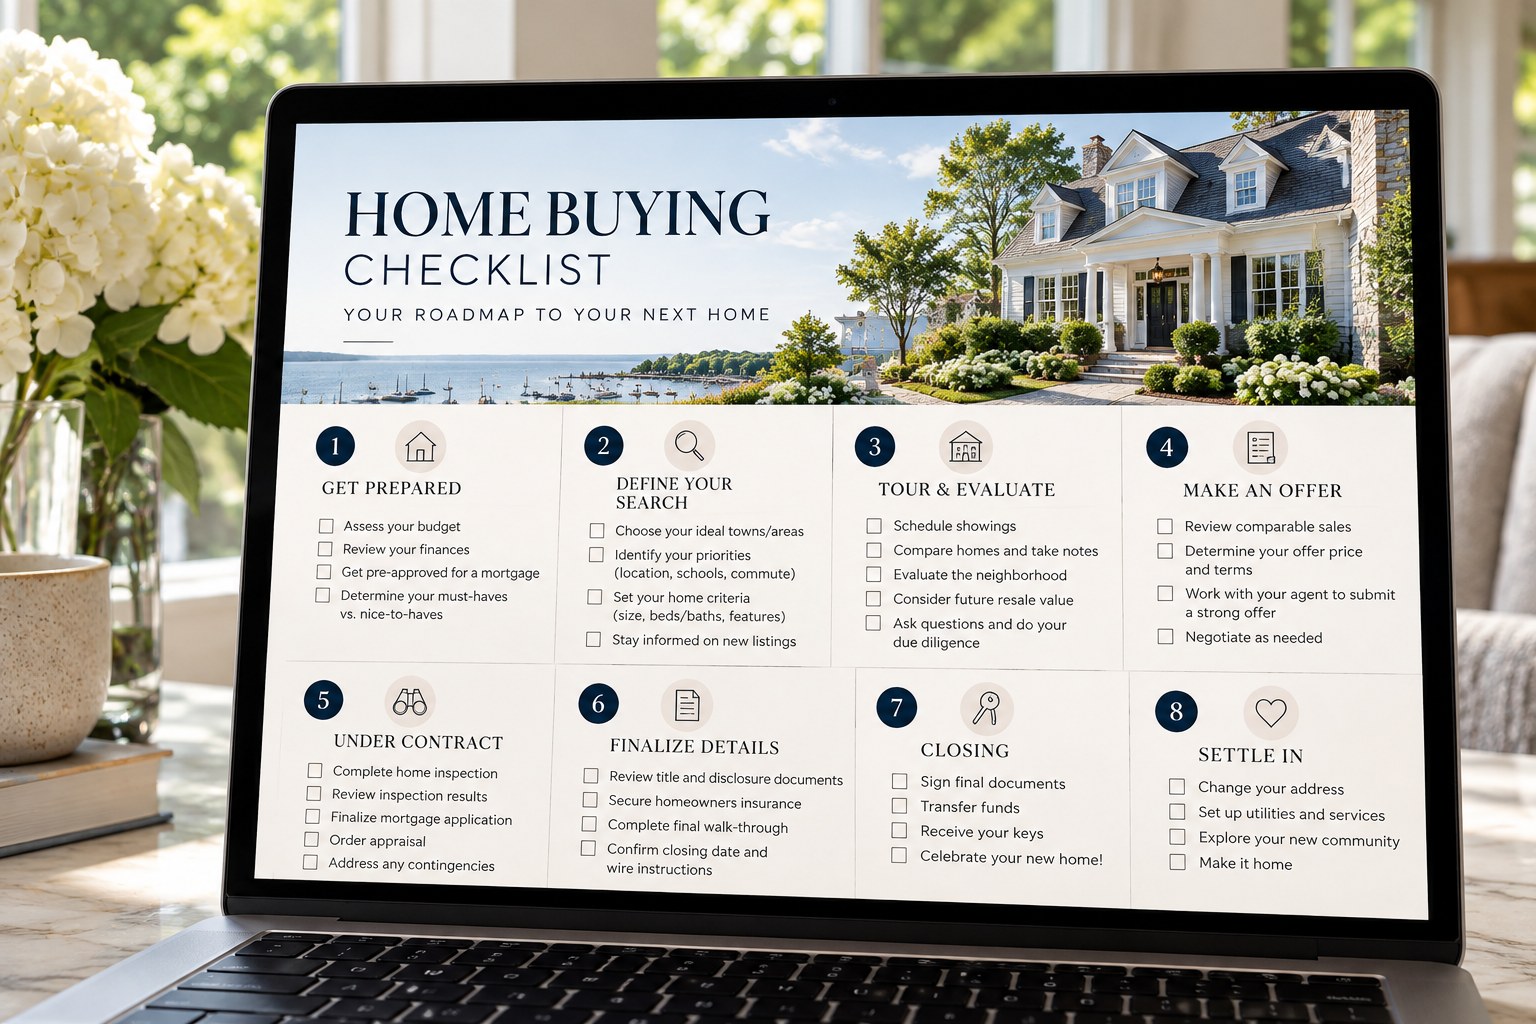
    Want the full step-by-step version? Get my free Home Buying Checklist, eight stages from getting pre-approved to getting your keys.


    Want the Complete Roadmap?

    This checklist is just one piece. My free 2026 Fairfield County Buyer Guide walks you through the full process — the 4-L Framework for choosing the right home, the complete due diligence playbook, and how to assemble your Pit Crew before you make an offer. Buying in Darien, New Canaan or Rowayton? Start here.


    Frequently Asked Questions

    What does a buyer’s agent do besides showing homes?

    A lot of the most valuable work happens behind the scenes. A buyer’s agent helps gather town records, flags questions for your attorney, coordinates inspections and insurance quotes, walks you through the seller’s disclosure, keeps your attorney, lender and inspectors on the same timeline, and helps you use what you learn to negotiate.

    What should I check before buying a house in Darien, CT?

    Check building permits and zoning with the town, confirm whether the home is on sewer or septic, look up the FEMA flood zone, get an insurance quote early, schedule a general inspection plus radon and any specialty inspections, and read the seller’s Residential Property Condition Report.

    Do Connecticut sellers have to disclose problems with the house?

    Yes. Connecticut requires sellers to provide a Residential Property Condition Report before the buyer signs a contract. If the seller doesn’t provide it, the buyer receives a $500 credit at closing.

    Is radon common in Connecticut homes?

    Radon can be found in homes across Connecticut, which is why the state recommends testing. The EPA recommends fixing a home if radon levels are 4 pCi/L or higher, and mitigation systems are common.

    Do I need a lawyer to buy a house in Connecticut?

    In Connecticut, real estate attorneys typically handle the purchase contract, title work and closing. It’s one of the first members of your team to line up.

    Buy With Confidence, Not Crossed Fingers

    This is likely the biggest purchase you’ll ever make and the most important asset your family will own. My Elite Buyer Representation is built to make the process clear, organized and well supported, from the first showing to the closing table.

    Thinking about buying in Darien, New Canaan or Rowayton? Let’s start with a free, no-pressure 20-minute strategy call.

    About the Author

    Anika Charron is a Senior Sales Associate with William Raveis Real Estate in Darien, CT, serving buyers and sellers in Darien, New Canaan, Rowayton and across Fairfield County. Contact Anika · Buyer Roadmap · Seller Strategy

  • Moving from NYC to Fairfield County CT – Your Complete Guide

    Moving from NYC to Fairfield County CT – Your Complete Guide

    Moving from NYC to Fairfield County CT  Your Complete Guide

    Every year, thousands of New Yorkers make the move to Fairfield County, Connecticut  and for good reason. Lower taxes than New York, more space, top-ranked public schools, and a direct Metro-North commute back to the city when you need it. But with so many towns to choose from, how do you know which Fairfield County community is right for your family? This guide breaks it all down.

    Why New Yorkers Are Moving to Fairfield County CT

    The value proposition is compelling. A home that costs $4M6M in Manhattan or prime Brooklyn can buy you a 4,000+ sq ft colonial with a yard, a top school district, and beach access in Darien or New Canaan for $2.5M-$4M+* Connecticut also has no city income tax, and property taxes  while not cheap  are significantly lower than comparable Westchester towns. Add a sub-60-minute commute on Metro-North and its easy to see why Fairfield County has been one of the top relocation destinations from NYC for decades.

    Darien CT: Best for Commuters and Families Who Want It All

    Darien is the gold standard for NYC commuter suburbs. With two Metro-North stations (Darien and Noroton Heights) offering sub-60-minute service to Grand Central, plus the #1-ranked school district in Connecticut, it consistently tops relocation lists. The newly developed Corbin District downtown and waterfront beach access make it a complete lifestyle package. Home prices start around $1.2M* for single-family homes and range up to $8M+ f*or waterfront estates.

    New Canaan CT: Best for Village Living and Architectural Elegance

    New Canaan offers the most picturesque village lifestyle in Fairfield County. Elm Street downtown feels like a film set  walkable, elegant, and lined with exceptional dining and boutiques. The school district rivals Darien for the #1 spot in Connecticut. The commute runs 6875 minutes to Grand Central (with a transfer in Stamford for most off-peak trains). Families with school-age children and buyers who appreciate Modernist architecture (home to Philip Johnsons iconic Glass House) gravitate here. Prices range from $700K* for condos to $8M+  *for estates.

    Rowayton CT: Best for Waterfront Village Life on a Tighter Budget

    Rowayton is Fairfield Countys best-kept secret. Technically part of Norwalk, this self-governing coastal village offers a rare tidal lifestyle  beaches, golf carts, lobster rolls, and a tight-knit community  with a direct sub-60-minute Metro-North ride to Grand Central. Its typically $300K-$500K*  less expensive than comparable Darien homes, making it popular with buyers who prioritize waterfront access over school district prestige (though Norwalk schools are solid).

    What to Know Before You Move: Practical Tips for NYC Relocators

    The Fairfield County market moves fast. Homes priced correctly in the $1.5M-$2.5M* range often receive multiple offers within days. Get pre-approved before you start touring. Consider the full cost of ownership: property taxes, HOA fees (if applicable), the Sixth Taxing District fee in Rowayton, and commuter rail passes. Most buyers who move from NYC prioritize being within a 5-minute drive of a Metro-North station  it makes the lifestyle seamless.

    Work with a Local Expert Who Knows the NYC Relocation Roadmap

    Anika Charron is a Senior Sales Associate at William Raveis Real Estate specializing in Darien, New Canaan, and Rowayton. Having guided numerous New York City buyers through the relocation process, Anika understands the unique tradeoffs  commute vs. school vs. waterfront vs. budget  that define every NYC-to-CT move. Contact Anika at anika@anikacharron.com to schedule your Fairfield County discovery tour.

    Market data source: William Raveis Real Estate, April 2026. Darien CT Single Family Median Sale Price: $3,002,500. New Canaan CT Single Family Median Sale Price: $3,045,000. Rowayton (Norwalk) CT Single Family Median Sale Price: $1,835,000. Data provided by REsource Analytix / SmartMLS.

    About the Author

    Anika Charron is a Senior Sales Associate with William Raveis Real Estate in Darien, CT, serving buyers and sellers in Darien, New Canaan, Rowayton and across Fairfield County. Contact Anika · Buyer Roadmap · Seller Strategy